France's rising debt servicing costs threaten financial stability
France's public debt stands at around 120% of GDP, and its borrowing-cost gap over German bonds is the widest since the eurozone crisis. Economists warn interest payments will climb sharply, yet the issue barely registers in political debate.
France, whose government lacks a parliamentary majority, is facing rapidly growing debt servicing costs. Public debt is roughly 120% of gross domestic product (GDP), and investors are demanding an ever higher risk premium. The matter extends beyond France, since it is one of the eurozone's largest economies.
The gap with Germany
France pays nearly 1.6 percentage points more than Germany on 10-year bonds. This difference, known as the spread, is the highest since the financial crisis and comparable to the level seen at the end of 2011 during the eurozone debt crisis. Since June 2026 it has more than doubled. Germany's debt is about 65% of GDP and it holds the top AAA credit rating, while France is rated AA, A+ or Aa3 depending on the agency, with several agencies assigning a negative outlook.
Friedrich Heinemann, an economist at the Leibniz Center for European Economic Research (ZEW) in Mannheim, describes the spread as a fever gauge for bond markets. If it rises too sharply, financing conditions deteriorate, banks get into trouble and the crisis can escalate.
Costs in the coming years
France is expected to pay more than €79 billion in interest on its total public debt in 2026, over €91 billion in 2027, and potentially €125–132 billion by 2030. These figures include social security funds and local authorities. The central government's interest bill alone is estimated by the Agence France Trésor, the French Treasury agency, at €62.6 billion. The country must refinance large volumes of bonds issued when rates were very low, while its budget deficit requires further borrowing. France last balanced its budget in 1974.
Politics and public opinion
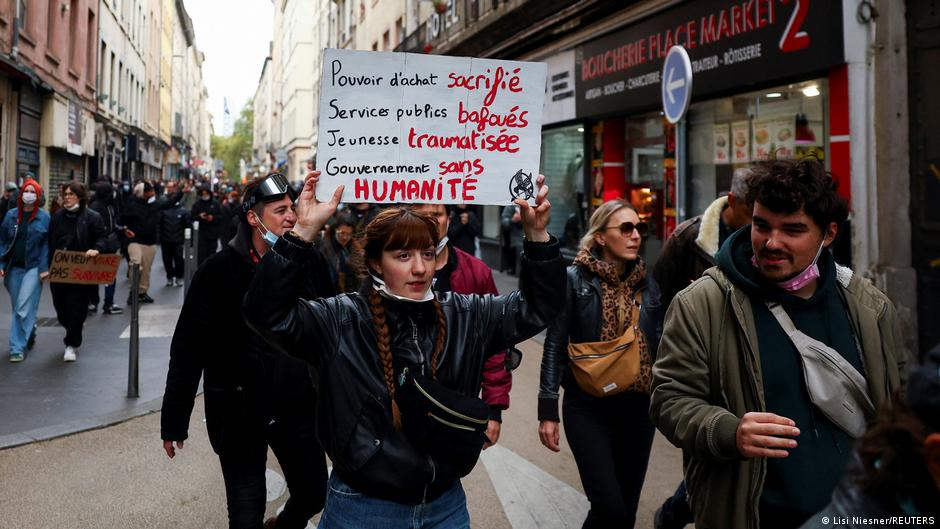
In response to nationwide protests, the government plans €4 billion in low-interest loans for school renovation by 2030 and a further €1 billion for universities by 2029. The far-right National Rally and the far-left La France insoumise are both campaigning on costly promises, which Heinemann calls economic fairy tales. Landry Charrier, a researcher at the University of Bonn, notes that according to INSEE, the French national statistics agency, 56% of the population receive more in benefits and services than they pay in taxes and contributions, so most have a tangible interest in keeping the status quo.
Heinemann also forecasts that German federal interest payments, currently around €30 billion, will more than triple by the early 2030s.